Portfolio Manager

• Insight
Circular Economy: an all-weather strategy for every market cycle
Adaptability is a hallmark of resilient investing. The Circular Economy strategy has demonstrated that discipline in action this year, navigating AI-driven market volatility while remaining focused on the long-term drivers of sustainable value creation.
Authors
Summary
Market dynamics are constantly changing as one cycle cedes to another. Frustratingly for managers, positioning that worked smoothly in one environment, oftentimes fails in another. The most resilient investment strategies tend to be those that can quickly adapt as markets evolve. It’s a distinction that continues to characterize the Circular Economy strategy since its inception in 2020. Though approaches have differed, what has been consistent is its ability to capture value, mitigate risks, and optimize returns in very different market environments.
The latest demonstration of that adaptability started in late spring when cracks in the AI trade emerged. AI is a powerful enabler of a circular economy, accelerating better resource management across a wide range of industries. Smarter software, automation, and digital tools help companies produce more output with fewer resources. They improve productivity, reduce waste, decrease costs, and optimize the use of energy, materials and capital.
The team has leveraged that strong alignment to build positions across the AI value chain, which have driven strong market returns. However, as enthusiasm for AI reached increasingly demanding levels, we began looking for opportunities elsewhere in the circular economy universe where fundamentals remained strong but where market expectations were more modest.
The portfolio’s AI positions worked well through much of H1. But in May, parts of the AI value chain began to show signs of outright euphoria, leading to crowded trades and expanding valuations. Sensing the downside risks were also rising, we began to rebalance the portfolio – reducing AI stocks which we viewed as overvalued, while adding non-AI stocks that had lagged the rally but whose fundamentals were improving. Those additions included quality holdings across industrials, healthcare, and materials. That process continued and even intensified over the summer, when many AI-related stocks saw sharp declines.
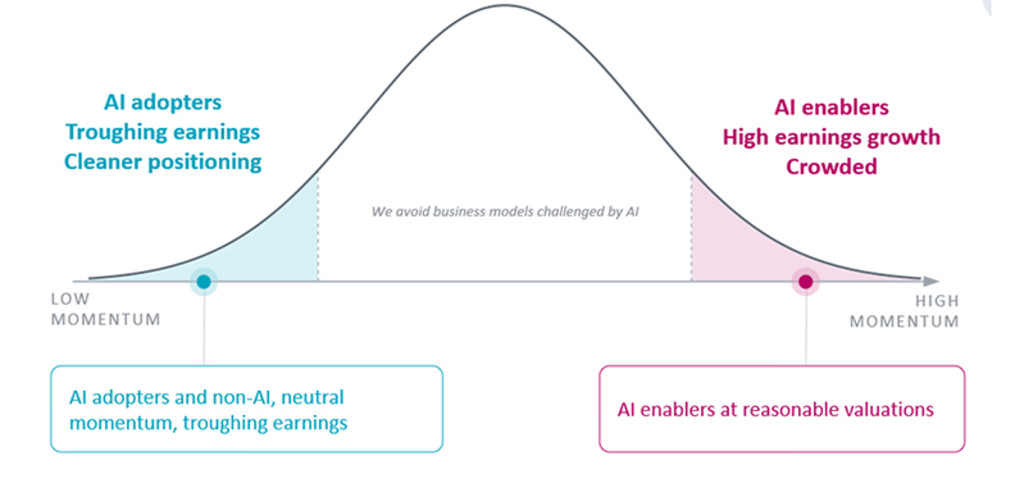
We like to describe this repositioning as our ‘barbell’ approach, which is what the portfolio resembles if its stocks were grouped into a distribution by earnings momentum (see Figure 1). At one end sit high-growth AI enablers while at the other sit high-quality, non-AI companies with lower valuations but attractive earnings potential. Together, the combination aims to balance participation in the ongoing structural growth of AI with exposure to companies where improving fundamentals are yet to be fully recognized by the market.
Figure 1 – The barbell in practice: balancing opportunity and reducing tail risks
Source: Robeco, August 2026.
Looking beyond AI
Shifts in market leadership are inevitable, even with a revolutionary technology such as AI. Revolutionary technologies naturally attract significant investor enthusiasm and capital but also create uncertainty, volatility and nervous speculation over just how long it can continue. But the upswing in non-AI stocks also reflects AI’s original promise – to accelerate innovation and growth across the entire economy, not just tech.
Evidence that AI innovation is expanding to other sectors is emerging. Healthcare providers are deploying AI to improve diagnostics and workflow efficiency. Industrial companies are using AI-driven automation to optimize production. Environmental services firms are applying digital tools to improve resource recovery, waste management and operational performance.
Circular Economy D USD
- performance ytd (31-7)
- 18.45%
- Performance 3y (31-7)
- 18.34%
- morningstar (31-7)
- SFDR (31-7)
- Article 9
- Dividend Paying (31-7)
- No
Past performance is no guarantee of future results. The value of the investments may fluctuate. Annualized (for periods longer than one year). Performances are net of fees and based on transaction prices.
The three-lens system
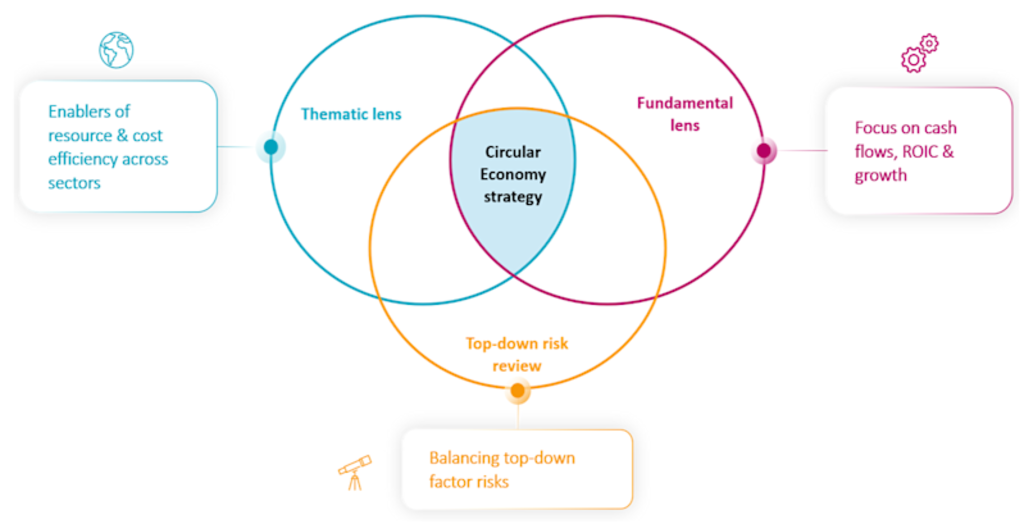
The approach is not simply an exercise in sector rotation. Stock selection is paramount because not every company is investment-worthy. The team relies on a systematic three-lens process for portfolio construction. The first lens is used to find companies which are creating value for their customers (for example, AI enablers whose products help their customers cut waste and improve efficiency).
The second lens is fundamental analysis. Companies must demonstrate attractive returns on invested capital, strong cash generation, healthy balance sheets and the potential to compound earnings over time. The third lens is risk management. This multi-layered framework helps monitor changing market conditions, manage factor exposures, and identify emerging tactical opportunities. It was through this lens that the team recognized early signs of excess in parts of the AI value chain and opportunities elsewhere in the market.
Figure 2 – Three lenses to make one resilient strategy
Source: Robeco, August 2026.
The risk lens
Continuous risk monitoring has been critical in helping the team adapt to changing market environments. It has played an important role in navigating periods characterized by very different sources of market leadership.
For example, throughout much of 2024 and early 2025, the Magnificent Seven drove a disproportionate share of global equity returns. This was not an ideal backdrop for a broadly diversified portfolio like Circular Economy, focused primarily on mid-cap companies rather than a narrow group of mega-cap technology stocks. Nevertheless, the strategy's diversified exposure and disciplined portfolio construction helped it navigate an environment dominated by a narrow group of stocks.
A distinctively different tack was applied back in 2022, in a period of Covid lockdowns and accelerating inflation (and later interest rates in response). Equity markets declined sharply and winners tended to be among financials and energy – sectors in which the strategy does not invest. Here the team positioned more defensively, investing in companies with stable earnings and recurring demand such as repair and upgrade businesses, waste management, environmental services, and healthcare. These companies helped preserve portfolio value during the pandemic. Similarly, the strategy adapted again in 2023 as leadership shifted to tech as the AI boom began.
An all-weather strategy
For investors, the appeal of thematic investing increasingly lies in its ability to combine long-term growth with pragmatic adaptability. Economic cycles will begin and end, each bringing innovation as well as new sets of winners and losers. The breadth of the Circular Economy’s investment universe helps it navigate these shifts, while remaining anchored to the themes of resource efficiency and asset productivity.
With an active share of more than 90%, the strategy differs substantially from the global equity index against which it is measured. That gives it more flexibility to pursue opportunities across sectors, regions and market capitalizations as opportunities evolve, an agility that large-cap, index-focused portfolios may struggle to match.
A broad investable universe, together with disciplined stock selection and risk management, has helped the strategy remain resilient through periods of uncertainty while continuing to identify the next sources of growth.
The recent market environment underscores that lesson.
What’s trending?
All the latest thematic investing trends just one newsletter subscription away.